
 Share


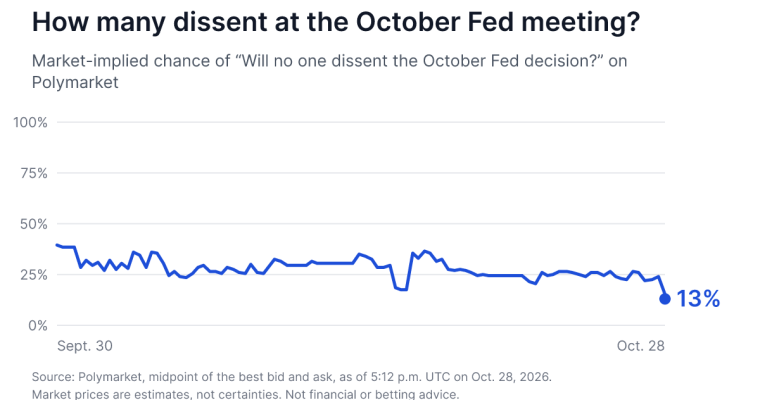
The Federal Reserve’s October 27–28, 2026 policy meeting is scheduled to conclude Wednesday, with Reuters reporting that at least one dissent is expected. Polymarket’s contract asking whether no one will dissent from the October Fed decision shows a market-implied chance of 13% as of Wednesday afternoon ET.
Key takeaways
- The October policy statement must record zero dissents for the no-dissent contract to resolve Yes.
- The no-dissent price has reversed its Oct. 16–17 rise, with trading volume running 3.2 times its recent weekly average.
- Reuters reported expectations of at least one dissent; CNBC’s survey reported expectations of at least two.
- A forecast that rates will stay unchanged is not a forecast of a unanimous vote.
The market separates two questions that can otherwise sound alike: whether the Fed leaves rates unchanged and whether every voting member supports its decision. Only the second question settles the no-dissent contract.
The no-dissent price reversed its mid-October rise
The contract rose from 18% on Oct. 16 to 37% on Oct. 17, a 19-point jump and its largest move inside 48 hours. The latest reading reverses that rise rather than extending it. The supplied reporting does not establish why the price moved.
Trading has also been busier than its recent baseline. Volume this week totaled $31,579, compared with a weekly average of $9,909 over the past month—a reported 3.2 times that average. That measures activity, not confirmation of a particular vote count.
The other contracts show where the listed alternatives stand. Polymarket’s exactly-two-dissents contract is priced at 43% as of Wednesday afternoon ET, the highest-priced listed outcome. Its exactly-one-dissent contract is priced at 23% as of Wednesday afternoon ET, while its exactly-three-dissents contract is priced at 21% as of Wednesday afternoon ET. These are separate estimates for exact counts, not a recorded vote or a forecast from the platform.
Reported dissent expectations sit above the zero-dissent test
The no-dissent contract requires zero members to dissent from the Fed Funds Rate decision at the October 27–28 meeting, as recorded in the FOMC statement. The meeting concludes Oct. 28, 2026; the statement resolves the market, and the rules give no separate resolution date.
Reuters reported that at least one dissent was expected. That minimum is at least one dissent above the zero required for Yes. Reuters also reported that BMO Chief US Economist Scott Anderson expected Cleveland Fed President Beth Hammack to dissent, possibly alongside others.
CNBC’s Oct. 27 survey reported that respondents expected at least two Fed voters to dissent from a decision to leave rates unchanged. That minimum is at least two dissents above the contract’s zero-dissent requirement. The reports differ in their stated minimum counts; neither supplies the actual vote.
A pause forecast does not measure unanimity
CNBC’s Oct. 27 survey drew responses from 30 people working in fund management, strategy and economics, with 93% expecting a pause at this meeting. Reuters separately reported on Oct. 28 that the Fed was expected to keep its benchmark rate steady.
Those outside views address the policy decision, while the lead contract measures unanimity. An unchanged rate decision can still draw dissent. The survey percentage and the no-dissent price therefore do not provide a directly comparable probability gap.
The distinction also explains why expectations of a pause can coexist with the market’s higher prices for dissent outcomes. Agreement on the announced rate is not the same as agreement among the voters.
October’s statement determines the other outcome
For the no-dissent contract to resolve No, the statement must record at least one member dissenting from the rate decision. Either reported dissent expectation would meet that condition if realized.
On Oct. 28, zero recorded dissents satisfies Yes; at least one defeats it, regardless of whether rates stay unchanged. The next scheduled FOMC meeting, Dec. 8–9, cannot move this October contract toward either outcome: December votes do not count.
—
Sources: As reported by Federal Reserve, Reuters and CNBC.
Market data: Polymarket, midpoint of the best bid and ask as of 5:12 p.m. UTC on Oct. 28, 2026.
Prediction market prices reflect the collective estimates of traders, not certainties. This is not financial or betting advice.